NR Inside-Bar Expansion
Narrow-range/inside-day H1 expansion.
EURUSD · H1 · Original trading hours
Source + EX5 + selected preset + checksums. Strategy Tester research build.
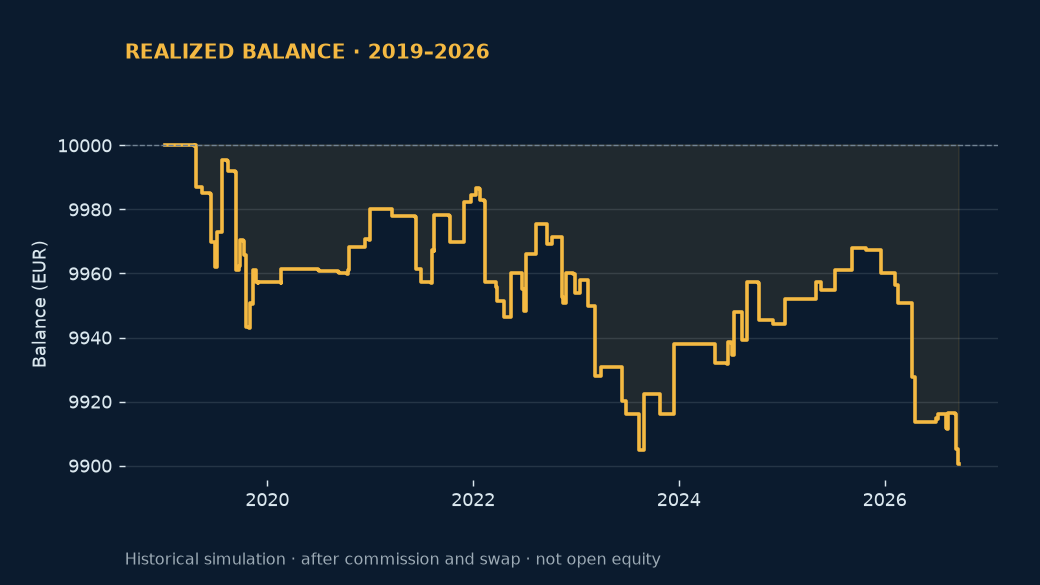
NR Inside-Bar Expansion
EURUSD H1 daily inside-bar/narrow-range expansion. Its February zero is a signal-window observation, not a removal decision.
Selected public preset
InputMode 5; InputVariant 0; RiskPercent 0.25; CampaignSession 0; CampaignSessionPolicy 1; CampaignBrokerWinterUTC 2; CampaignBrokerDST 1.
Rule and risk mechanics
A completed D1 bar must be inside the prior D1 bar and its range no larger than every preceding six ranges; equality passes. During the next broker day, a completed H1 close beyond the setup high/low enters. Stop is 1.5 D1 ATR(14), no target, tester-only maximum 48 hours. Setup is consumed before order success. Source controls: 0.25% equity risk, 1.5% daily brake, 2-pip spread gate, deviation 10, 7-per-lot estimate.
Relationship to the strategy library
Related only by narrow-range family: NR7 Volatility Breakout uses strict NR7, EMA(50), stop entries, opposite-extreme stop and 2R; this variant needs an inside day and H1 close breakout. See the legacy EA map for mapping scope.
Follow-up: entry and 48-hour exit observed
The unchanged selected public EA sold 0.02 lots of EURUSD.TFQ1 at bid 1.07513 on 7 May 2024 at 22:00:00 broker time, after the completed H1 close broke below the eligible inside/NR7 day. It bought back at ask 1.07817 on 9 May at 22:00:00, exercising its 48-hour time exit. The test ran from 7 May inclusive to 13 May exclusive, at broker UTC+3: 198,895 real bid/ask ticks, 1 signal, 1 entry and 1 managed exit, with no tester-forced close. This directly demonstrates that this preset can trade.
The event was selected by the first chronological qualifying source signal after February, not by its return. Price P/L was −$6.08; recorded swap +$0.13; final balance $9,994.05 from $10,000. Added commission and delay were zero; native financing history is unverified. The 30-calendar-day interval from 7 April has no release exclusions. MT5 can load older indicator history, so this is not a complete indicator-seed, stop-loss, sizing, restart or profitability validation.
Earlier February 2024 observation
The receipt had no entries or exits; a separate approved-M1 replay also found no qualifying February setup. That does not establish that the EA never trades. The approved new diagnostic window is 2024-02-01 inclusive to 2024-03-01 exclusive, on EURUSD.TFQ1 H1, with Model 4, a USD 10,000 deposit and 1:100 leverage at broker UTC+2. It added no commission or delay; recorded native swap history is unverified. It is separate from older archived broker charts and reports. It is not a profitability, restart, or full-rule-coverage result.
The earlier February warmup limitation remains part of that historical observation. The separate May follow-up above now demonstrates one entry and its time exit; it does not prove all branches.
Package documentation and download; exact selected preset and binary identity: selected preset SHA-256 026e4e36a50b722d6e1f4552ac19dc7d603ab9d00721504f0b436f053286f62f; package binary SHA-256 dde5445864f4d1abfe84c60bdfdde05c0de4f13f595d09a454eae78f8a2ff01f. Public functionality status: JSON evidence.
Selected configuration: rolling-year net EUR -44.94; full-period net EUR -99.40. Negative confirmation is retained in the archive.
How this strategy works
- Requires the previous D1 bar to be an inside bar and the narrowest range in the Variant 0 seven-day comparison.
- A closed H1 bar expanding beyond that prior daily range opens the trade with a 1.5 ATR stop.
- The trade closes after 48 hours; variants 1 and 2 use 10/14-day narrow-range tests and 2.0/2.5 ATR stops.
The selected configuration uses EURUSD / H1, variant s0. All indicator and session values used by this build are listed in the preset editor.
Measured backtests
| Period / model | Net EUR | PF | Trades | Equity DD | Native report |
|---|---|---|---|---|---|
| Development 2019.01.01 → 2024.01.01 M1 OHLC screening | -61.94 | 0.78 | 63 | 1.14% | MT5 report |
| Validation 2024.01.01 → 2025.01.01 M1 OHLC screening | +6.46 | 1.20 | 8 | 0.25% | MT5 report |
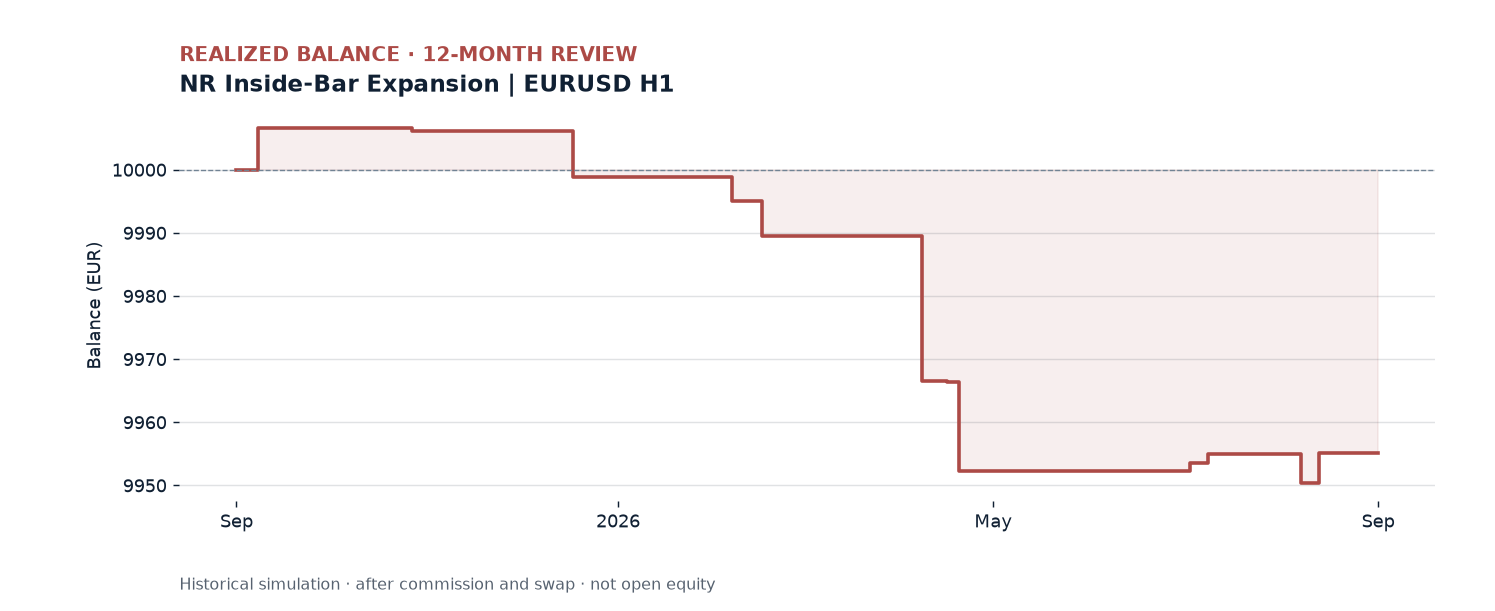
| 12-month review 2025.09.01 → 2026.09.01 Real-tick mode + fallback | -44.94 | 0.24 | 11 | 0.79% | MT5 report |
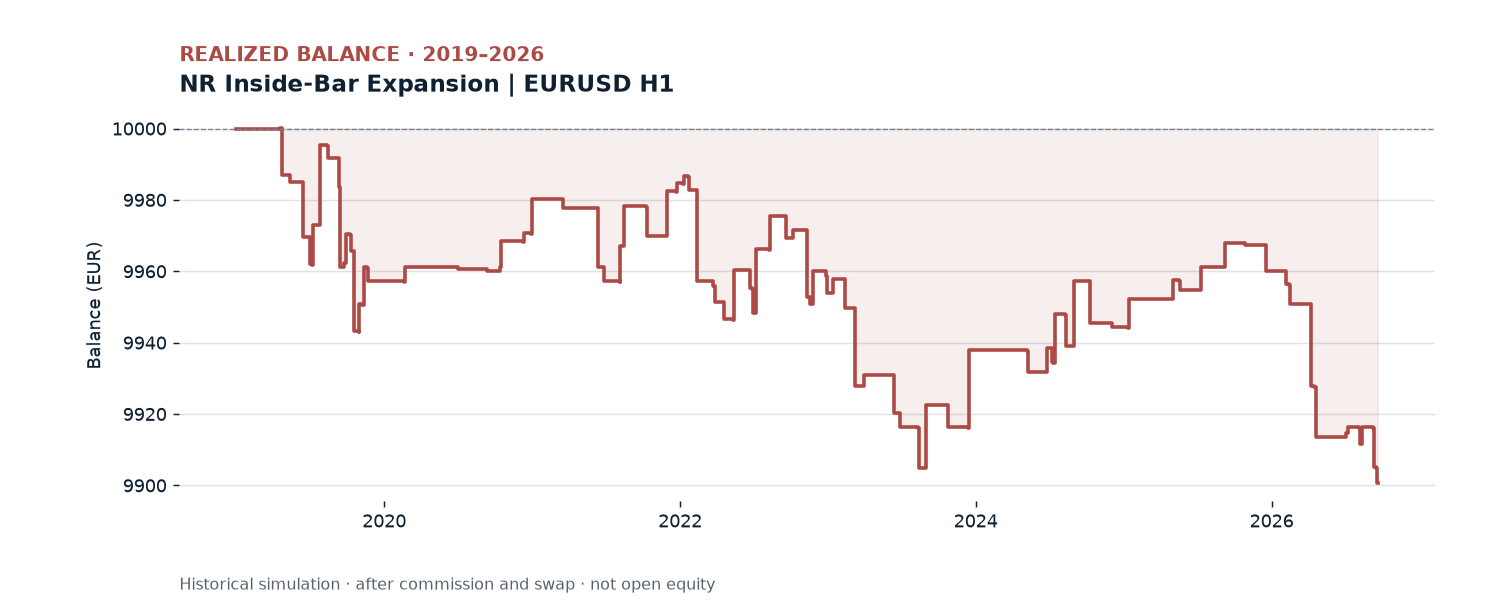
| Long review 2019.01.01 → 2026.09.21 Real-tick mode + fallback | -99.40 | 0.75 | 88 | 1.15% | MT5 report |
Adjust the strategy preset
MT5 also validates parameter combinations and may reject incompatible inputs. Session modes use local London, New York and Tokyo hours. Broker-time conversion uses the configured winter UTC offset and DST rule. A session filter limits eligible entries; it does not change the underlying strategy signal or create trades where none qualify. Policy 2 also closes before the chosen session ends.
Install and reproduce the archived broker test
- Download and extract the ZIP. Copy
TFPriceResearch_Sessions.ex5intoMQL5/Experts/TradeForexin the MT5 data folder. Keep MQ5 and all MQH headers together if compiling. - Open Strategy Tester, select the EA, EURUSD and H1. The build rejects normal chart execution.
- Load the included
selected-test.setor a preset downloaded above. Symbol, chart timeframe, dates, deposit and tick model are tester settings outside the .set file. - For confirmation choose “Every tick based on real ticks”, EUR 10,000, 1:30 leverage and 100 ms delay. Use 2025.09.01–2026.09.01 or 2019.01.01–2026.09.21; retain the generated report and Journal.
- Allow MT5 to obtain the available broker history. Compare actual date coverage, costs, trade count and history quality; a later download or different broker server can change the result.
Read the general MT5 installation guide; this package’s tester-only restriction takes precedence over normal chart-activation steps.
Limits of the archived broker results
- Tested values are research settings, not a profitability claim.
- Broker history, spread, swaps and fills can change outcomes.
- These are retrospectively selected historical tests. Development, validation and review periods overlap previously inspected history; this is not a fresh independent holdout.
- The balance plots show realized outcomes. Equity drawdown includes floating positions and must not be inferred from the balance line alone.
- Available native ticks and fallback are accepted. Missing ticks, historical spread paths and cost assumptions limit confidence; profitable history does not guarantee future profitability.
- RiskPercent is an entry-sizing estimate, not a hard loss cap. Costs, gaps and slippage can exceed that estimate; some legacy sizing excludes transaction costs.
Additional cost stress adds 25% of the absolute commission and swap amounts: 12-month stressed net EUR -46.11; long-period stressed net EUR -108.31. This is not a full spread or slippage stress.
Files and reproducibility
Each ZIP includes MQ5 source, required headers, EX5, README, selected-test.set, selection.json and SHA256SUMS.txt. Compiled builds and measured results are unchanged by this documentation update.
ZIP SHA-25607762f0aa2cc6c111ee1cc363701d48c6d01a17d9887cac0b999875fcfde9150
Tested EX5 SHA-256dde5445864f4d1abfe84c60bdfdde05c0de4f13f595d09a454eae78f8a2ff01f
Selection criteria and all strategy categories · Frozen selection record